Jessica Lopez has had two separate home insurance claims open since early July, and as of late August she still had no firm timeline from her carrier on either one. She’s one of a wave of Chicago-area and northwest Indiana homeowners stuck in a storm-damage claims backlog, and adjusters say a hidden coverage gap, thin or nonexistent sump pump protection, is quietly making it worse.
Key Points
- Two rounds of severe storms hit the Chicago area and northwest Indiana this summer, on July 3 and Aug. 11, 2026, leaving some homeowners managing overlapping claims at once, according to ABC7 Chicago.
- State Farm alone logged almost 50,000 home and auto weather-related claims in Illinois between June 19 and mid-August, according to Shaw Local.
- Illinois recorded 178 tornadoes by mid-July 2026, more than any other state in the country this year, Shaw Local reported.
- Public adjuster Ryan Ward of Guru Claims Services says missing or inadequate sump pump coverage is “the biggest thing” he’s running into on basement flooding claims right now, he told ABC7 Chicago.
A Summer of Overlapping Claims
Lopez’s ordeal started with the first storm. Severe weather on July 3 knocked out power across her Homewood neighborhood, and the outage disabled her sump pumps long enough for water to back up into her basement, causing water damage and mold growth, she told ABC7 Chicago. She was still working through that claim, gathering contractor estimates and waiting on her insurer, when a second storm hit on Aug. 11. It downed trees in her yard, broke windows and started a roof leak.
“It has not been a summer,” Lopez told the outlet. “You know, kids are depressed, trying to manage, trying to keep the house as salvageable as possible, to find out what insurance is going to do, and at the same time, try fixing what you can on your own.”
By late August, an adjuster still hadn’t walked through her property. “My assessor is not scheduled to come out until September 1st,” she said. “So that is a long period of wait. Until then, what do you do?”

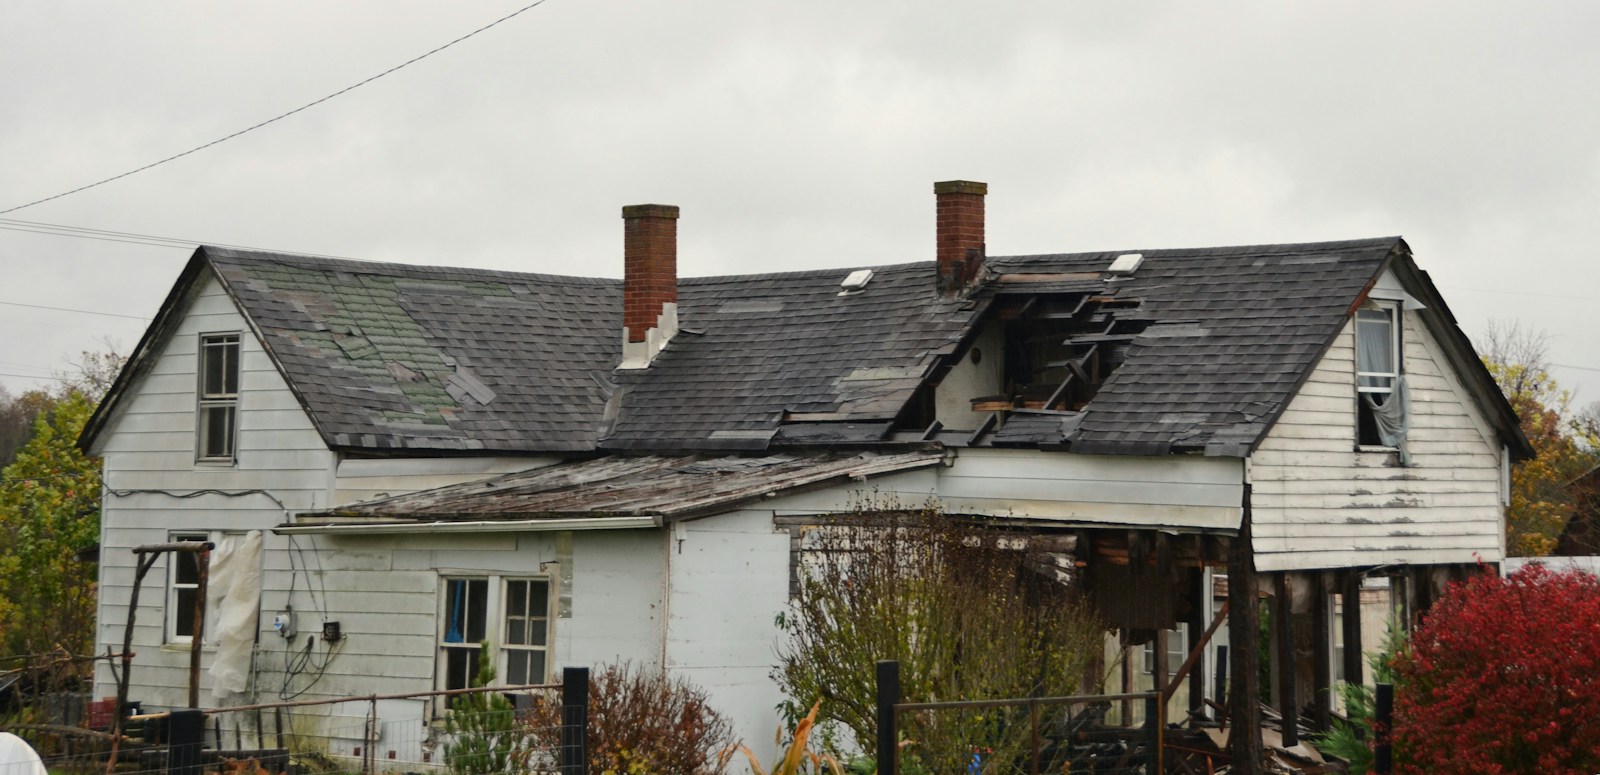
Storm debris piled outside a home after a summer storm. Homeowners across the Chicago area have faced similar cleanup this season. (Photo: Troy Mortier / Unsplash)
The Sump Pump Coverage Loophole
Lopez isn’t alone in running into gaps in her coverage. Ryan Ward, a public adjuster with Guru Claims Services who represents homeowners in disputes with their insurers, says basement water damage is dominating his caseload this summer. Sump pump coverage, he says, is usually the sticking point.
“Basements. The biggest thing I’m doing right now,” Ward told ABC7 Chicago. “I went to two clients today. They don’t have enough sump pump coverage or no sump pump coverage at all.”
The gap is structural, not incidental. Water backup and sump-overflow protection is typically excluded from a standard homeowners policy by default and sold only as a separate endorsement carrying its own, often modest, coverage limit, according to insurance attorney Chip Merlin of Merlin Law Group. Even homeowners who do buy that endorsement aren’t guaranteed a payout: insurers often lean on broad exclusion language covering water that “escapes or overflows or discharges, for any reason” from a sump system, layered with anti-concurrent-causation clauses that let one excluded cause sink an otherwise valid claim. Merlin points to a recent case, Tinkelman v. Liberty Mutual, in which a homeowner with two fully functioning sump pumps was still denied coverage after a compressed discharge pipe let his basement flood. It’s proof, he wrote, that “an exception to an exclusion does not create coverage.”
A Record Storm Season Strains the System
The backlog isn’t confined to one insurer or one neighborhood. Illinois is on pace for its highest catastrophic insurance claim volume in a decade, and the state had already logged 178 tornadoes by mid-July, more than any other state in the country this year, according to Shaw Local’s reporting, which cited State Farm figures showing the insurer alone fielded almost 50,000 home and auto weather claims statewide between June 19 and mid-August.
Those numbers land on top of an already costly stretch for Illinois homeowners. The average Illinois policyholder now pays $2,731 a year for home insurance, about 14% above the national average, with premiums up 68% since 2020, the seventh-largest increase in the country, according to CBS2 Chicago’s analysis of insurance rate data published earlier this summer.
Meanwhile, state and local officials are still assessing whether the Aug. 11 storms qualify for federal disaster aid. Teams from FEMA and the Illinois Emergency Management Agency have been going door-to-door in south suburban Cook County documenting flood depth and structural damage for a request to the governor’s office, ABC7 Chicago reported in early September. Cook County’s past requests for that kind of federal help have been turned down before, which only adds pressure on private insurers to cover more of the gap on their own.
What Homeowners Can Do While They Wait
Some homeowners hesitate to file a claim at all, unsure whether it’s worth the wait or the risk to their premiums. Michael Balarezo, CEO of the claims-assistance company Adjusto, says building a paper trail early is the smarter move regardless of that uncertainty.
“There’s nothing stopping folks from getting an estimate from a contractor or a specialist who does this sort of remediation work for the type of damage that you have, and I urge folks to get at least three different estimates,” Balarezo told ABC7 Chicago.
For Lopez, the frustration isn’t really about the money. It’s about what the wait says about the coverage she’s spent years paying into. “It hurts because you know you pay your bills on time,” she said. “You make sure your home is protected because you put value into your home. You work hard for what you have, and you want it to last.”
Leave a Reply