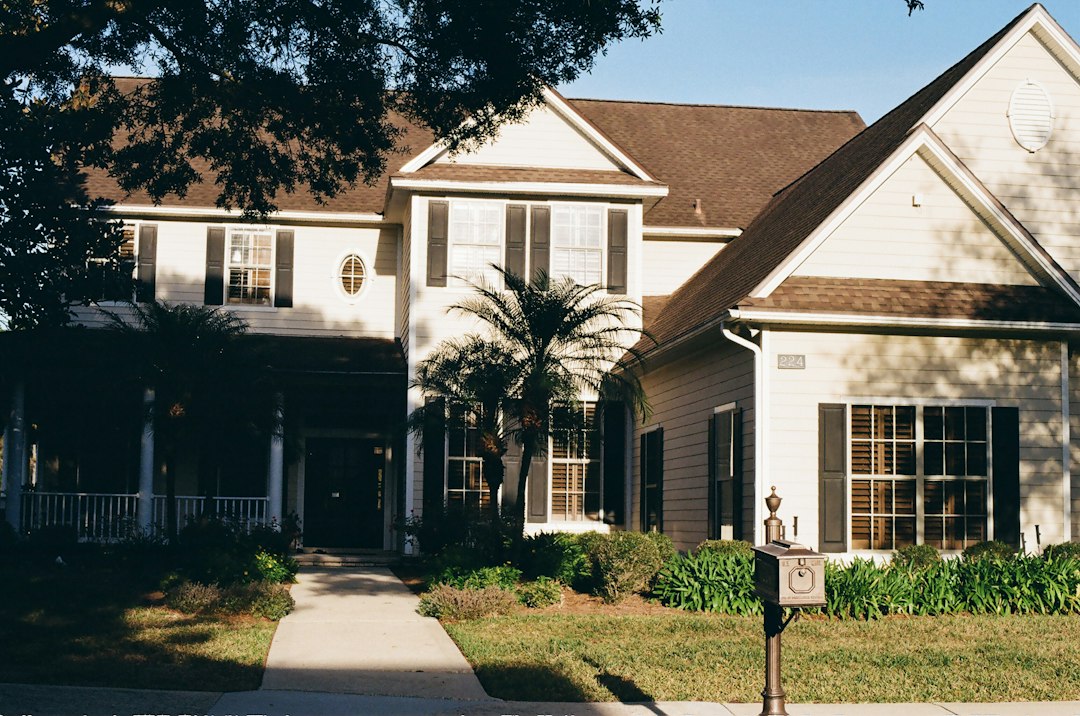
Few financial decisions carry as much emotional weight as the one @hailey_julia.ramos (TikTok) opens up to her audience about: her daughter has asked her to risk her fully paid-off house to help finance something, and rather than deciding alone, she’s turning directly to her followers for perspective on a genuine, unresolved family conflict playing out in real time.
A paid-off home represents one of the most significant financial milestones a person can reach, the complete elimination of what’s typically the largest recurring expense in a household budget. Putting that asset at risk, whether through a home equity loan, a reverse mortgage, or simply adding the home as collateral, isn’t a decision most homeowners take lightly, which is exactly why this request from an adult child carries such emotional complexity.
There’s a reason this kind of financial crowdsourcing, turning to an online audience rather than a financial advisor or family mediator, has become such a common format. Beyond the practical value of gathering varied perspectives, there’s a genuine comfort in processing a difficult decision publicly, finding that other people have faced similar dilemmas, and hearing a range of viewpoints that a single trusted advisor or even a close friend might not offer.
This scenario also touches on a genuinely difficult intergenerational financial dynamic that’s become increasingly common as housing costs and general cost of living have outpaced wage growth for younger generations. Parents who worked hard to pay off a home free and clear are increasingly being asked to leverage that hard-won equity to help adult children facing a financial landscape that’s considerably more difficult than the one their parents navigated.
It’s worth considering the asymmetry of risk embedded in a request like this one. The daughter, presumably, stands to gain significant benefit if the financing goes through and whatever it’s funding succeeds, while the mother bears the entire downside risk to her home, her primary and often only major asset, if circumstances change and repayment becomes difficult. That imbalance is likely a core part of why this decision feels so fraught.
There’s also a broader financial literacy conversation worth having around using home equity as a lending source for family members generally. Financial advisors typically caution against risking a primary residence, an asset that provides genuine housing security, for purposes that don’t directly build equivalent long-term value, a principle that applies whether the money is going toward a home purchase, a business venture, or something else entirely.
This kind of content also reflects a meaningful cultural shift in how financial decisions get discussed at all. A generation ago, a dilemma like this would have stayed entirely within the family, discussed quietly if at all. The willingness to bring genuinely difficult, unresolved financial and family tension into public view represents a real departure from that privacy, for better or worse.
There’s also something worth noting about how home equity specifically has become a central character in so many family financial stories. As a paid-off house increasingly represents one of the only substantial assets many families hold, especially compared to previous generations who may have had more diversified savings, it’s taken on an outsized role as the de facto emergency fund or family bank for major life decisions.
In the end, what makes this story resonate isn’t a resolution, since there may not be a clean one to offer. It’s the honest portrayal of a dilemma that countless families quietly navigate without ever discussing it openly, the genuine tension between supporting a child’s future and protecting the financial security a parent spent a lifetime building.
Leave a Reply