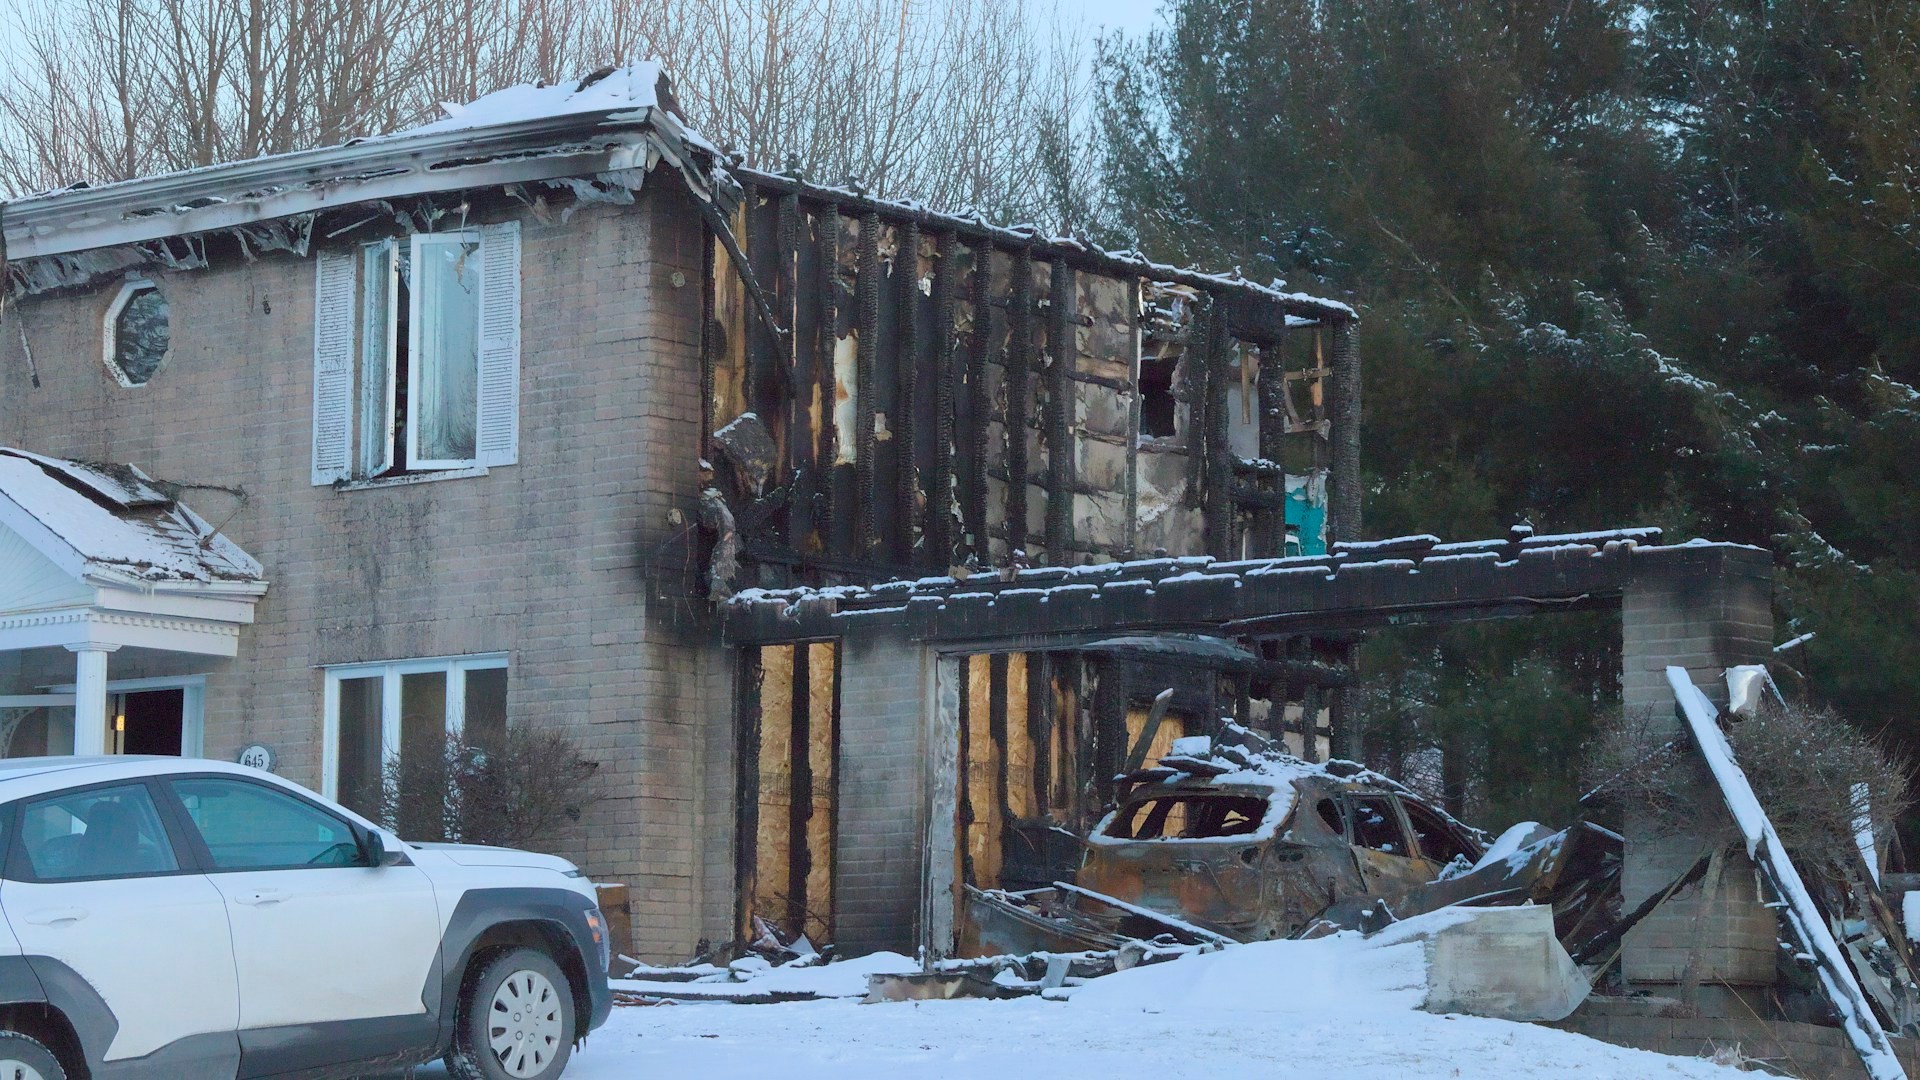
You pay the premium every year, and you expect the company to be there on the worst day. A new analysis suggests that for some large insurers, a claim often ends with no money at all. Fifteen large homeowners insurers closed at least half of their 2025 claims without any payment, according to Weiss Ratings.
The firm published its findings on April 16, 2026, after reviewing the insurers’ 2025 financial statements. The numbers are worth a careful look before your next renewal notice shows up.
One Texas Insurer Closed 78% Of Claims Without Paying
The range in the Weiss analysis is wide. On the low end of the group of 15, Stillwater closed 50% of its claims with no payment. At the top, Mid-Century Insurance Co. of Texas closed 78%.
That means roughly four out of every five claims at the Texas company ended without a payment, according to Weiss. Other names on the list include Lemonade at 64% and Spinnaker at 61%.
These are not tiny companies. Weiss looked at large insurers, the kind that write policies for many thousands of homeowners and advertise widely.
Some Insurers Closed Only A Small Share Of Claims Without Payment
The same report found a very different picture elsewhere in the market. Ten insurers were at 20% or lower. So the gap between companies is huge, from a fifth of claims or fewer closed without payment at some insurers to more than three quarters at another.
That spread is the most useful thing in the data. It tells you that the company you choose can matter a great deal, and that the figures are not simply a fact of life with every insurer.
Closed Without Payment Is Not The Same As Denied
It is important to read these numbers fairly. A claim closed without payment is not automatically a claim that was wrongly turned down. Weiss makes the point that closed without payment is not the same as denied.
Many claims end with no check for ordinary reasons. The damage may be smaller than the deductible, so the policy pays nothing. A homeowner may file and then withdraw the claim after getting a repair quote. The loss may fall under an exclusion that the policy clearly states.
Those cases explain why some share of claims at any insurer ends with a zero. The figures in the Weiss analysis are a signal worth investigating, not proof that any one company treated its customers badly.
Why A High Number Is Still Worth Your Attention
Even with those caveats, a share as high as 78% is a long way from a share of 20% or less. The difference may reflect where an insurer writes its business, what kind of policies it sells, or how it handles claims. It may also mean that customers at some companies have a harder path to getting paid.
You do not need to settle that question to act on the data. If you are shopping for coverage, a claims record is one more piece of information alongside price, coverage limits and the company’s financial strength.
A cheap premium can look like a bargain until the day you file a claim. The savings are real only if the insurer pays when it should.
What To Check Before You Renew
Start with your policy. Read your declarations page and note your deductible, the coverage limits, and any separate deductibles for wind or hail. Know what your policy excludes, since those exclusions are a common reason claims end with no payment.
- Look up your insurer’s name in the Weiss analysis and see whether it is among the 15.
- Ask your agent how many claims the company pays and how it handles disputes.
- Check your state insurance department website for complaint records.
- Get at least two or three quotes, and compare coverage, not just price.
If your own insurer is on the list, do not panic. Call your agent, ask direct questions about claims handling, and compare it with other companies before you decide.
How To Protect Yourself When You File A Claim
Good habits can make a difference whatever company you use. Keep a home inventory with photos or video of your belongings and every room. Store the files somewhere safe, away from the house, such as in the cloud.
When damage happens, take photos before you clean up, make temporary repairs to prevent further harm, and keep every receipt. Put your claim in writing, and keep notes of every call, including the date, the name of the person and what was said.
If a claim is turned down, ask for the reason in writing. You can request a review, get a second opinion from a contractor, and contact your state insurance department if you think the decision is unfair.
The Bottom Line For Homeowners
The Weiss analysis found that 15 large insurers closed at least half of their 2025 claims without paying, with one Texas company at 78%. It also found that ten insurers were at 20% or lower. That contrast shows why renewal is the moment to ask questions.
Do not let a renewal slide by on autopilot. A half hour of reading your policy, checking your insurer’s record and comparing quotes could save you from a very unpleasant surprise down the road.
More Stories You May Like
- Closing Costs Hit Buyers With Title Fees Escrow Prepaids And HOA Transfer Charges Many Never Budgeted For So Read The Loan Estimate Early
- Fresh Paint And Staging Can Hide Water Stains Uneven Floors And Musty Smells So Walk Through With A Checklist Before You Fall For The Listing Photos
- Renters Keep Losing Security Deposits Over Move Out Mistakes They Could Have Fixed With A Phone Camera And A Few Minutes Of Paperwork
Leave a Reply