Buying a home is supposed to be a step toward financial stability. For one condo owner, it has become the opposite — a monthly bill that keeps climbing on an asset that keeps losing value.
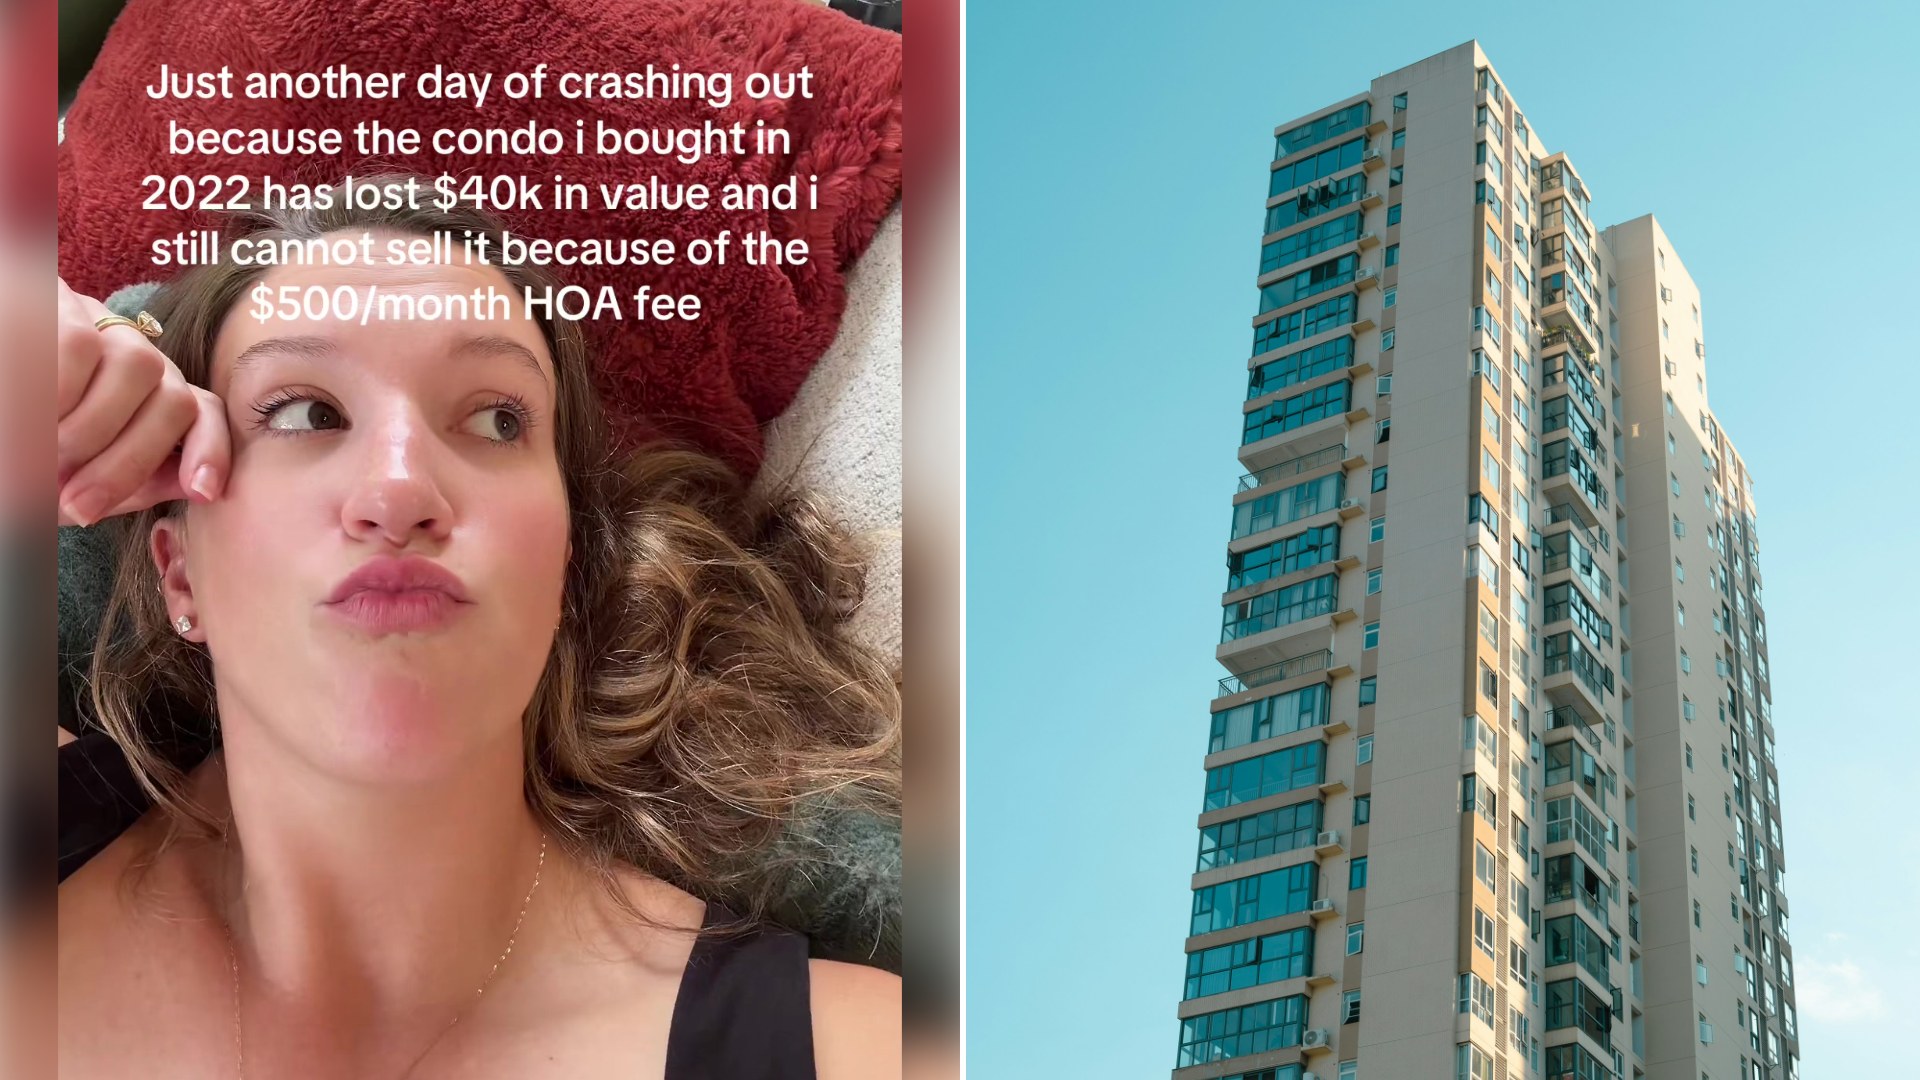
A creator posting on TikTok as @abbyrosecw laid out the situation plainly in her caption: “Has anyone else been fcked by this market & a high condo HOA fee???” According to the video, she shares her frustration and financial stress about owning a condo that has lost value while carrying a steep HOA fee — a combination that leaves her, by her own account, stuck.
The video doesn’t specify exact numbers for the drop in value or the size of the fee, but the tone makes clear this isn’t abstract complaining — it’s the kind of monthly math that keeps a homeowner up at night. Watching an asset most people are told to treat as an investment instead become a liability, while still being on the hook for association dues regardless of the unit’s worth, is a specific and increasingly common kind of financial squeeze.
The video’s reach — 1.2 million views on an account with just 2,300 followers — suggests this isn’t a one-off complaint. It’s a story a lot of condo owners in similar markets seem to recognize immediately, judging by how far it traveled beyond her existing audience.
For a lot of condo owners, the appeal of ownership was supposed to be building equity instead of paying rent to someone else. When the math flips — falling values paired with rising mandatory fees — that promise can start to feel more like a trap than an investment, which is exactly the frustration coming through in her video.
The particular sting of this situation is the asymmetry: a mortgage payment is fixed and predictable in a way an HOA fee often isn’t, and a falling market value doesn’t come with any adjustment to what’s owed each month regardless of what the unit could actually sell for if she tried.
When a Condo Purchase Turns Into a Financial Trap
Condo ownership comes with a financial variable a lot of buyers underweight at purchase time: the HOA fee isn’t fixed, and it isn’t optional. Fees can rise sharply to cover rising insurance costs, deferred maintenance, or special assessments for major repairs — and unlike a mortgage payment, there’s often little a homeowner can do to negotiate it down.
Before buying into any HOA or condo association, it’s worth reviewing the association’s financial reserves, recent fee history, and any planned special assessments — documents most sellers are required to disclose. A healthy reserve fund is a good sign; a thin one is often a preview of steep fee hikes to come.
If you’re already in a situation where fees have climbed and value has dropped, a few paths are worth exploring: attending HOA board meetings to understand exactly where the money goes, asking about fee assistance or payment plans if you’re struggling, and, if selling isn’t realistic right now, talking to a housing counselor (many nonprofit ones are free) about options. It’s a genuinely hard spot to be in, and it’s one more homeowners are finding themselves in as insurance and maintenance costs climb across the board.
It’s also worth asking whether your HOA is following its own governing documents when raising fees — most associations are required to hold votes or provide advance notice for significant increases, and a homeowner has the right to request meeting minutes and budget documents to understand exactly how a fee decision was reached. Sometimes the process reveals a legitimate need; other times it reveals mismanagement worth challenging.
If you’re weighing whether to hold or sell in a similar spot, a conversation with a HUD-approved housing counselor (a free service in most areas) can offer an outside, non-commissioned perspective on the numbers — often a useful gut-check before making a decision under financial stress.
You can watch the full video and follow @abbyrosecw on TikTok for more.
Leave a Reply