A real estate content creator is breaking down a specific listing to show buyers how to read between the lines of marketing language that sounds upbeat on the surface but actually signals a seller in a weaker position than the photos suggest. In the video, @ex3tecno walks through phrases pulled directly from a real listing description and explains what each one tends to mean in practice once a buyer learns to decode it.
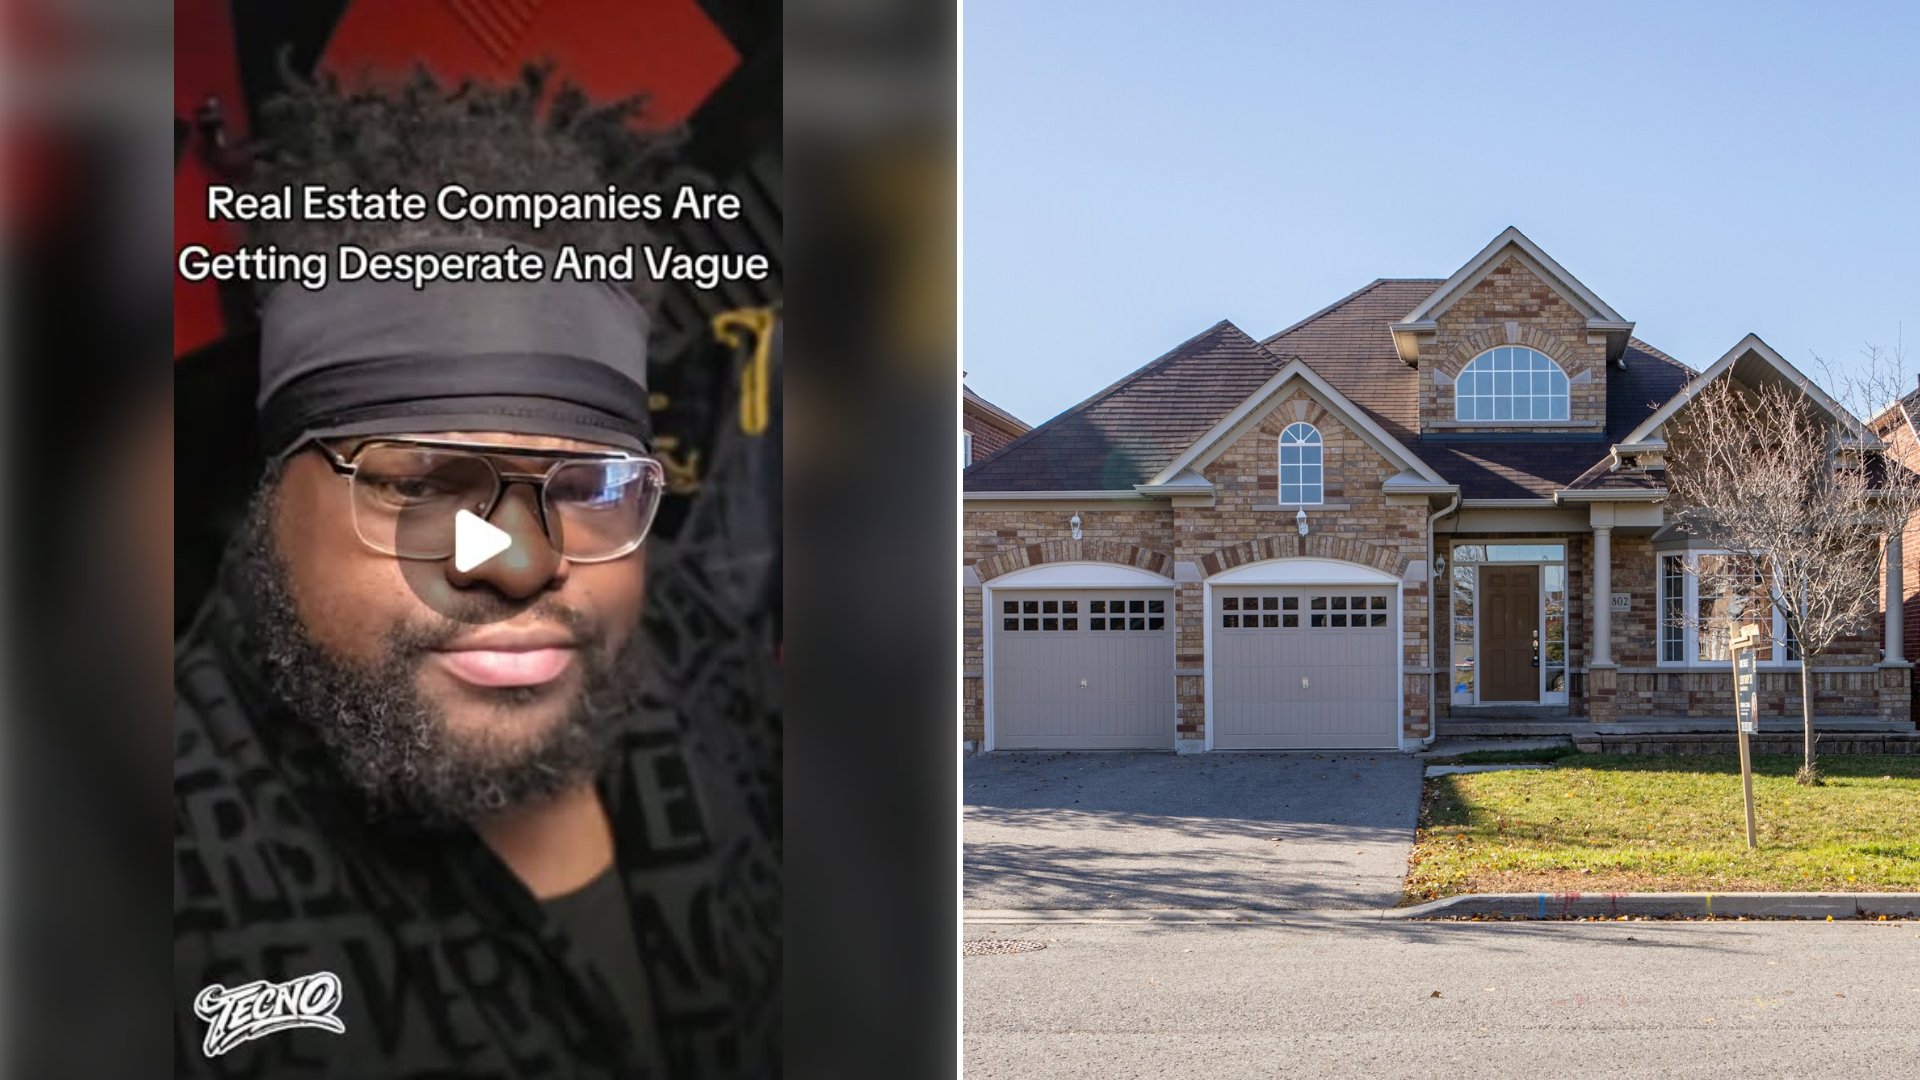
The video points out that certain phrases show up far more often once a market starts cooling, including language that emphasizes motivation over features, like describing a seller as highly motivated or open to all offers, or listings that lean on vague positivity such as calling a home full of potential rather than describing anything concrete about its condition. None of these phrases are dishonest on their own, but a creator who reviews listings regularly can start to notice when the tone of an entire local market shifts in the same direction at once.
That kind of language shift tends to track closely with harder numbers. When a housing market cools, two of the clearest early indicators are rising inventory, meaning more homes sitting on the market at once, and longer average days on market, meaning homes take longer to sell than they did in a hotter stretch. Real estate data providers track both figures closely because they tend to move before sale prices do, giving a preview of where pricing is headed before it shows up in closed sale data.
Buyers can check both of these numbers for free through most major real estate websites, which publish median days on market and total active listings by metro area and often by individual zip code. A rising days-on-market figure combined with a growing number of active listings in the same area is one of the more reliable signs that supply is starting to outpace demand locally, which is exactly the kind of environment that tends to produce more motivated-seller language in new listings.
Price history is another detail buyers often skip past but shouldn’t. Most listing platforms show a record of price changes on a given property, and a pattern of one or more reductions since the home first went on the market is a direct, unambiguous signal that the original asking price did not generate enough interest. Combined with vague or motivation-heavy listing language, a visible price cut history tells a buyer they may have real room to negotiate rather than needing to match the asking price to compete.
Listing language isn’t the only place this kind of signal shows up either. Agents and sellers in a cooling market also tend to offer more concessions upfront in the listing itself, such as covering a portion of closing costs or offering a credit toward repairs, details that are far less common to see advertised when a market is moving quickly and multiple offers are expected. Noticing these specific concessions mentioned directly in a listing is often a more concrete tell than tone alone.
None of this means every listing using soft or motivated language is automatically a great deal, since plenty of sellers use that phrasing simply because it is standard industry practice regardless of market conditions. The real value in learning to read listings this way is combining the language with the harder data: days on market, price history, and local inventory trends together paint a far more reliable picture than any single listing description on its own. For buyers trying to figure out how much negotiating power they actually have in a given market, that combination of reading comprehension and basic data checking can end up being worth far more than any single insider tip.
More from Willow and Hearth
- Freddie Mac Survey Puts the Average 30 Year Fixed Mortgage Rate at 7.40 Percent for October 8, Adding About $24.50 a Month to a $300,000 Loan Compared With the Week Before
- National Association of Realtors Says the Typical First Time Buyer Is Now 40 Years Old and Puts Down 10 Percent, According to Its 2025 Profile of Home Buyers and Sellers
- Consumer Financial Protection Bureau Says to Compare Three Groups of Fees on Your Loan Estimate and Closing Disclosure Because Some Can Never Rise and Others Can Change by Any Amount
Leave a Reply