The homeowners behind @oursevernhouse made a decision that drew skepticism from people around them: they sold their previous home specifically to bring down their mortgage, then poured three years into renovating the older, smaller house they bought instead. Their latest before-and-after showcase lays out just how far that renovation has come.
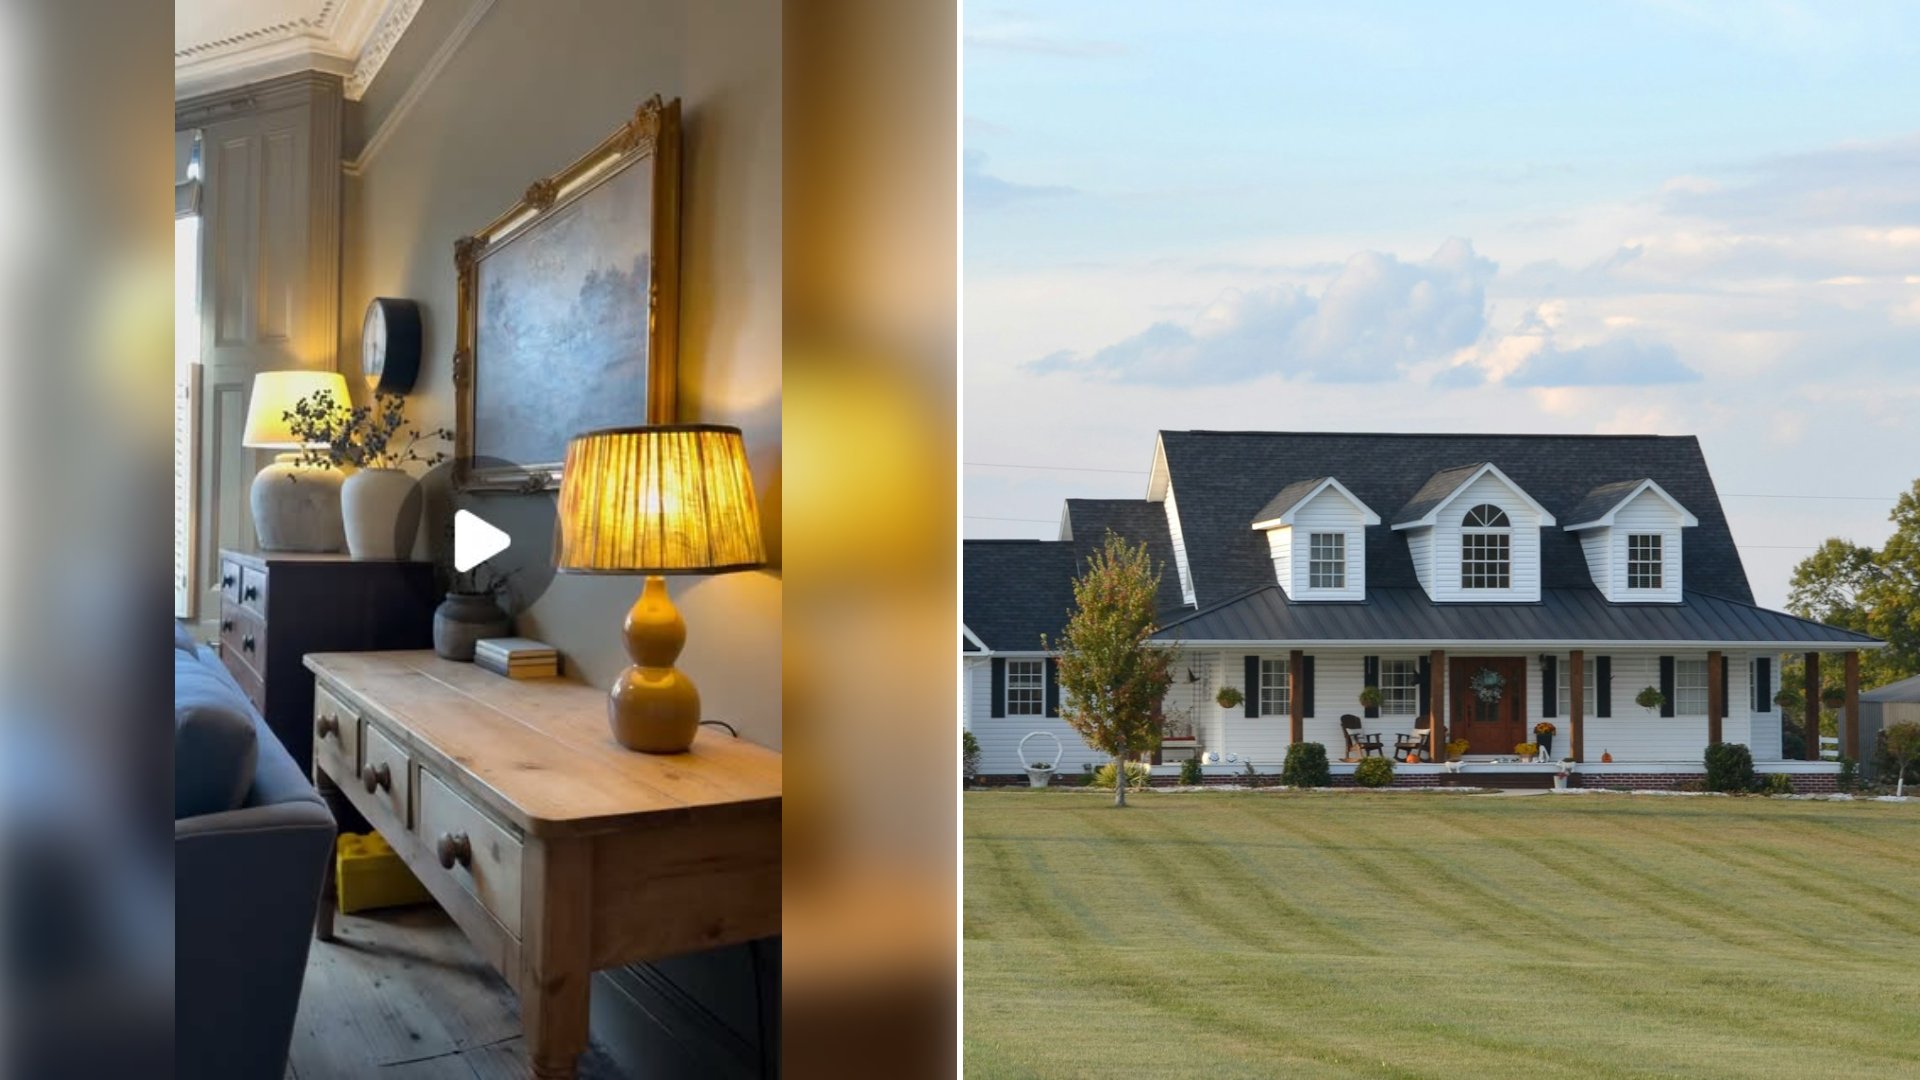
The interior shots move room by room, contrasting the dated, worn condition the house was in when they bought it against the renovated version taking shape today. It is the kind of slow, visible progress that only becomes convincing over a long timeline, and three years of documented work is exactly what makes the comparison land. The couple has been open that the decision to downsize was financially motivated from the start, which gives the renovation footage a second layer: it is not just a home improvement story, it is a vindication story.
Choosing to sell a home specifically to shrink a mortgage payment runs against a common instinct to trade up rather than down, which is likely why the couple says people warned them against it. Watching three years of renovation progress unfold in a smaller, cheaper house answers the skepticism in the most direct way possible: by showing the house becoming the home they wanted, on their own terms and their own budget.
What downsizing a mortgage actually does to long-term finances
The math behind a decision like this is well documented, even if it is not always intuitive. A smaller mortgage balance means a smaller required monthly payment, which immediately frees up cash flow that can go toward savings, renovation costs, or simply financial breathing room. Because home loans are amortized, a lower principal also means significantly less total interest paid over the life of the loan. On a 30-year fixed mortgage, the interest portion of each payment is heavily weighted toward the early years, so reducing the loan amount up front has an outsized effect on total interest paid over the full term compared with a larger loan at the same rate.
Lower mortgage payments also directly affect debt-to-income ratio, a figure lenders use to evaluate borrowers for any future financing. Freeing up a larger share of monthly income by downsizing can make it easier to qualify for other credit, including financing for a renovation itself, which is relevant for a couple funding a multi-year remodel. Housing economists also point to reduced mortgage stress as a meaningful factor in household financial stability more broadly: housing costs are typically the single largest line item in a household budget, and a mortgage payment that consumes a smaller share of income leaves more room to absorb unexpected expenses, from a job loss to a major repair, without falling behind.
There is a tradeoff, of course. A smaller, older home often needs more work to bring it up to a desired standard, which is exactly the renovation investment this couple has been documenting for three years. But because that investment is typically paid down gradually, as cash allows, rather than financed entirely upfront through a larger mortgage, it tends to carry less long-term interest cost than simply buying a larger, already-updated home with a bigger loan in the first place.
More from Willow and Hearth
- Freddie Mac Survey Puts the Average 30 Year Fixed Mortgage Rate at 7.40 Percent for October 8, Adding About $24.50 a Month to a $300,000 Loan Compared With the Week Before
- National Association of Realtors Says the Typical First Time Buyer Is Now 40 Years Old and Puts Down 10 Percent, According to Its 2025 Profile of Home Buyers and Sellers
- Consumer Financial Protection Bureau Says to Compare Three Groups of Fees on Your Loan Estimate and Closing Disclosure Because Some Can Never Rise and Others Can Change by Any Amount
Leave a Reply