A TikTok creator is breaking down a homeownership path she says most renters have never even heard of, combining a Section 8 housing voucher with a separate nonprofit lending program to buy a brand new home with no down payment required. In the video, she walks through how the two pieces fit together and why she believes the combination is one of the most underused tools available to lower income renters trying to become owners.
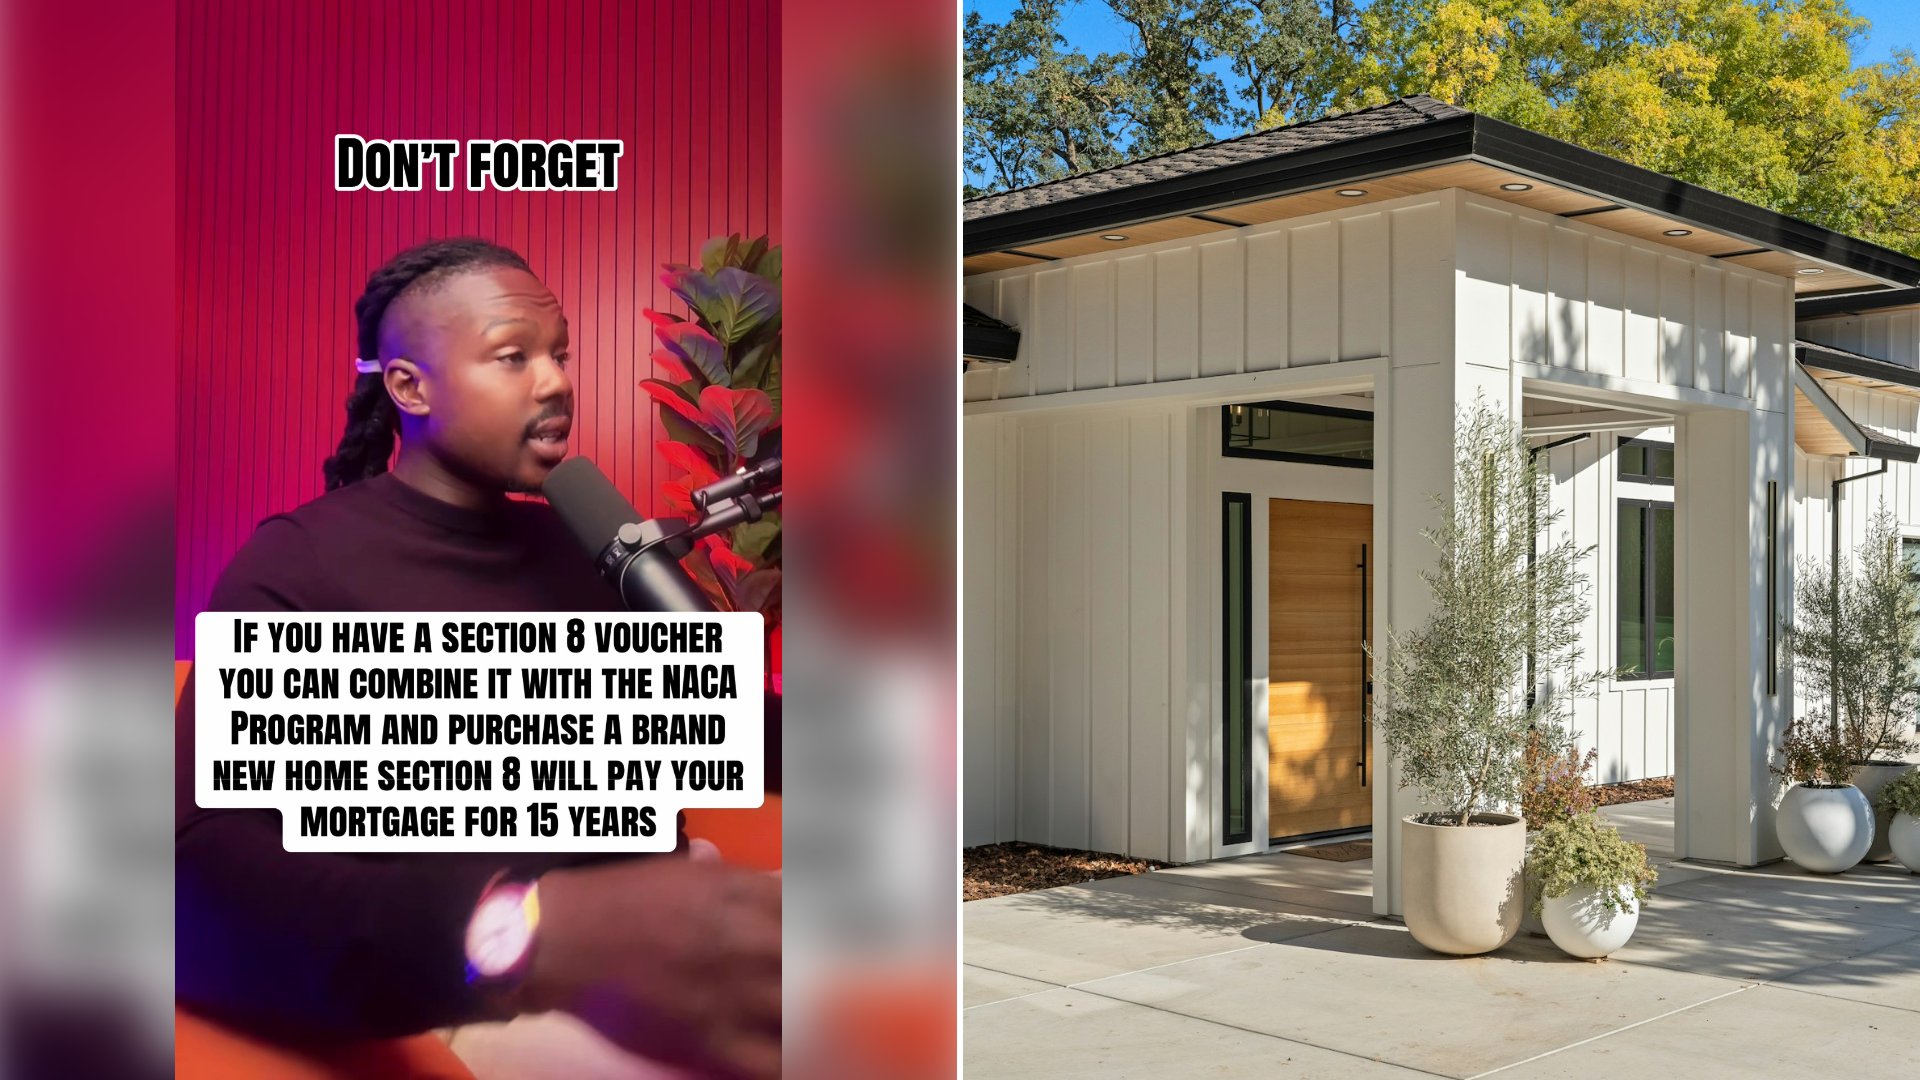
The explanation, posted by creator @.mylifeordebt, centers on the Section 8 Homeownership Voucher Program, a lesser known branch of the standard Section 8 rental voucher program that allows qualifying households to apply their voucher toward mortgage payments instead of rent. She pairs that with NACA, the Neighborhood Assistance Corporation of America, a nonprofit homeownership program known for requiring no down payment and no closing costs for members who complete its process.
@.mylifeordebt
Both programs are real, but the details matter more than a single viral clip can usually cover. The Section 8 Homeownership Voucher Program is not available everywhere. It is offered at the discretion of local public housing authorities, and participants typically need to meet minimum income and employment requirements, along with first time homebuyer status in most cases, before a voucher can be used toward a mortgage rather than rent. Not every housing authority that administers Section 8 rental vouchers also runs a homeownership version, so eligibility depends heavily on where an applicant lives.
NACA’s side of the equation is where the no down payment, no closing cost structure comes from, and it is genuinely one of the most borrower-friendly homeownership programs in the country. However, NACA membership requires completing a multi-step process that includes financial counseling, document verification, and a qualification review, and the process can take several months from first workshop to a qualified purchase. While NACA is widely described as having no minimum credit score requirement, it is more precise to say NACA does not rely on a FICO score the way conventional lenders do. The organization still reviews an applicant’s full payment history, debt levels, and savings pattern through its own underwriting process, so approval is not automatic simply because a credit score requirement is waived.
That distinction matters for anyone watching this kind of video and hoping it describes a shortcut. Combining a homeownership voucher with NACA can meaningfully lower the barrier to buying a home, particularly for renters who have steady income but little saved for a down payment. It is not, however, a guaranteed approval path, and both halves require patience, paperwork, and in many cases, geographic luck depending on whether a local housing authority offers the voucher option at all.
Still, for renters who assumed homeownership required a traditional down payment and a strong credit score, learning that programs like these exist, even with their real requirements attached, can reframe what feels possible. The comments on the video reflect exactly that reaction, a mix of people hearing about the voucher option for the first time and others sharing their own experiences going through NACA’s process.
More from Willow and Hearth
- Consumer Financial Protection Bureau Says to Compare Three Groups of Fees on Your Loan Estimate and Closing Disclosure Because Some Can Never Rise and Others Can Change by Any Amount
- Federal Housing Finance Agency Raises the 2026 Baseline Conforming Loan Limit to $832,750 and Caps High Cost Areas at $1,249,125, Which Leaves Some Buyers Still Borrowing Jumbo
- National Association of Realtors Says the Typical First Time Buyer Is Now 40 Years Old and Puts Down 10 Percent, According to Its 2025 Profile of Home Buyers and Sellers
Leave a Reply