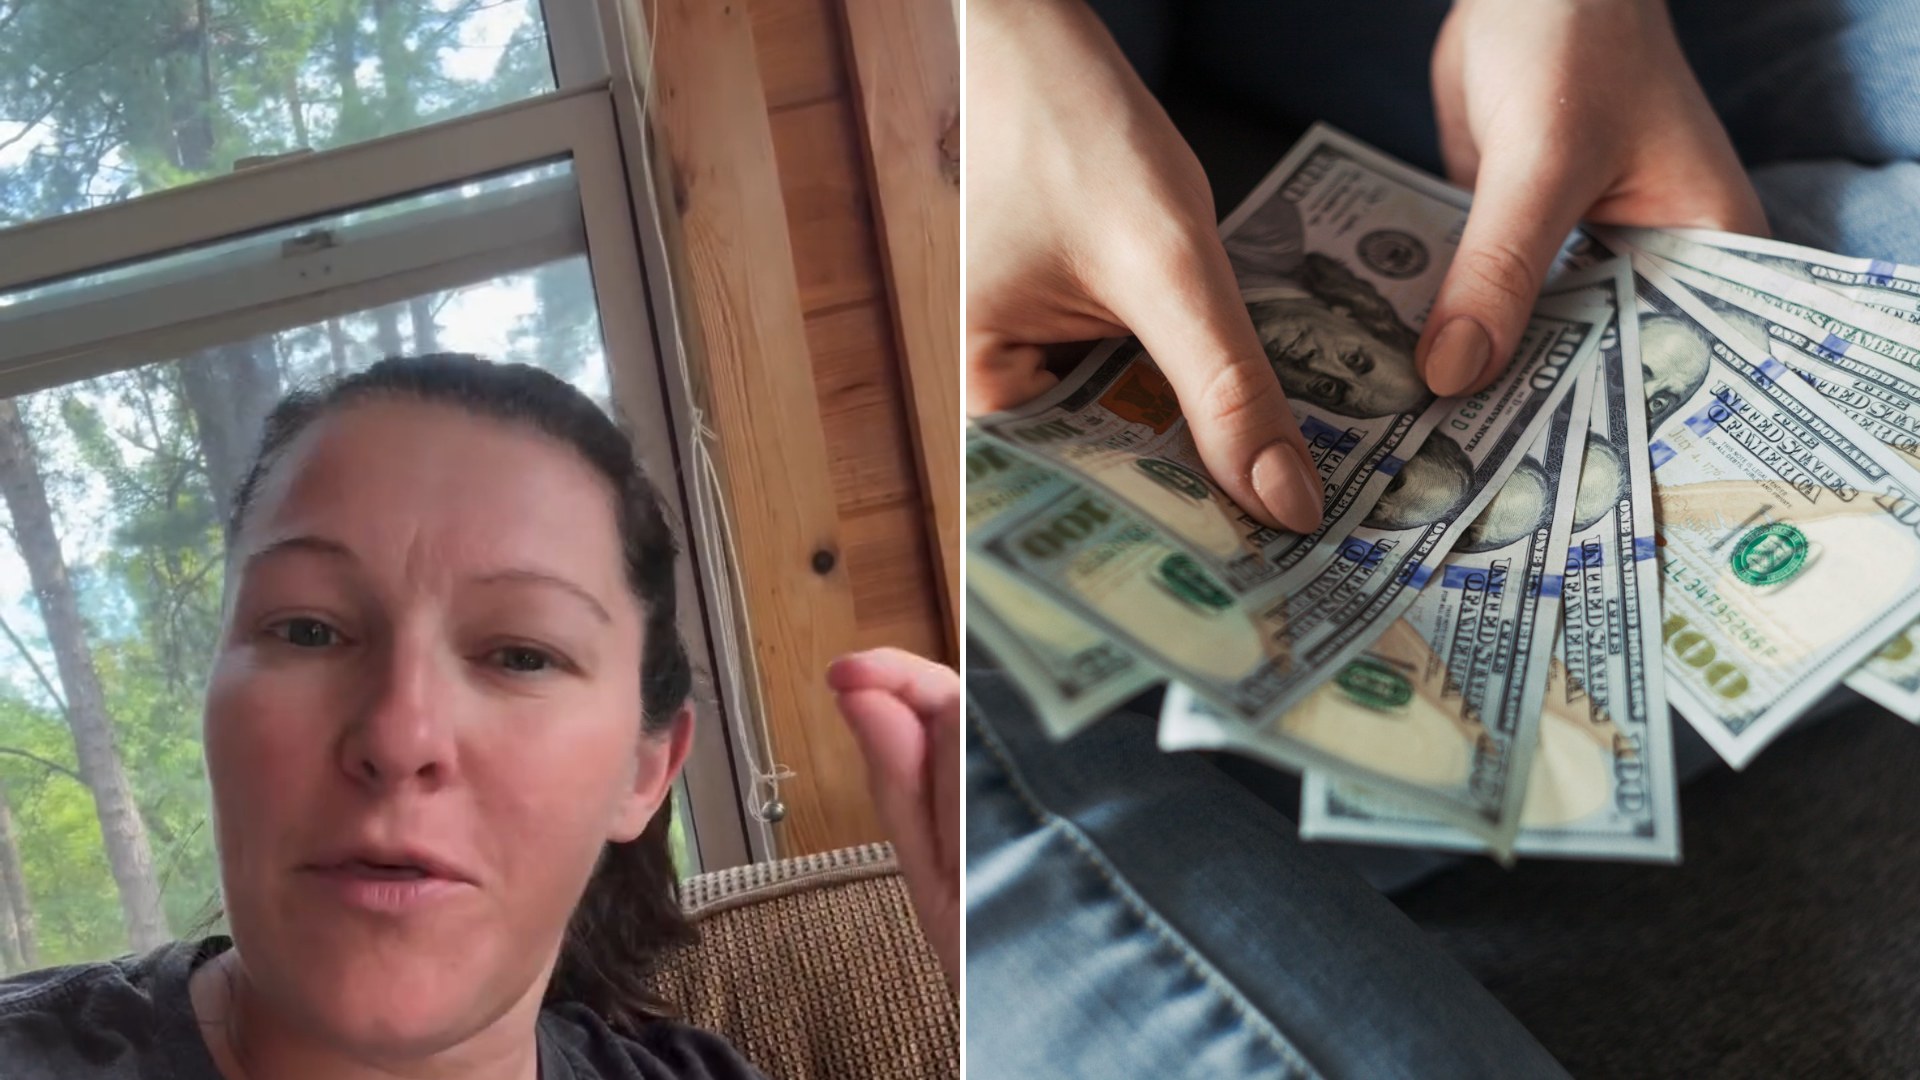
A routine trip to the bank turned into an uncomfortable moment of questioning for one creator — and it’s left her wondering exactly what she’s obligated to answer when she’s simply trying to withdraw her own money.
Posting on Instagram as @debteach20, she opens the video with clear frustration: “What the heck?? It’s none of your business! These bank tellers…just do your job, click the links,…” According to the video, she shares a personal, frustrating story about a bank teller asking her what she plans to do with cash she’s trying to withdraw — a question that, in the moment, felt to her like an overstep.
The video doesn’t specify the amount involved or the exact wording of the teller’s question, but the sense of indignation is unmistakable: a simple transaction turned into something that felt, to her, invasive. It’s a situation a lot of people have some version of — standing at a counter, being asked to justify a decision about your own money to someone you’ve never met.
Clearly, the moment struck a chord with a much wider audience than her existing following — the video has been watched 1.5 million times on an account with 1,100 followers, a reach that suggests plenty of viewers have faced a similar exchange at their own bank and had the same instinctive reaction.
Moments like this tend to leave a lingering unease even after the transaction is complete — a nagging sense of having been treated as a suspect rather than a customer, simply for handling your own money the way you chose to.
It’s a moment that highlights a tension in how banks are asked to operate: protecting customers and the broader financial system from fraud on one hand, while treating each customer’s routine transactions with a baseline of trust and privacy on the other — a balance that doesn’t always feel struck correctly from the customer’s side of the counter.
What You’re Actually Required to Tell a Bank Teller
It can feel intrusive when a bank employee asks what a cash withdrawal is for, but there’s a regulatory reason those questions sometimes come up: U.S. banks are required under federal law to monitor for signs of fraud and money laundering, and large or unusual cash transactions can trigger internal reporting requirements regardless of how routine the withdrawal feels to the customer.
That doesn’t mean every question is required or that a teller is entitled to a detailed explanation — policies vary by bank and by the size of the transaction, and you’re generally not legally obligated to explain your reasons for withdrawing your own funds below reporting thresholds. If a question feels excessive, it’s reasonable to ask the teller to clarify why it’s being asked, or to speak with a branch manager if the exchange feels uncomfortable.
For larger withdrawals, it can help to call ahead — many banks appreciate advance notice for big cash transactions anyway, since branches don’t always keep large sums on hand, and a heads-up can make the process faster and less fraught for everyone involved. Knowing your bank’s specific policy before you’re standing at the counter is usually the best way to avoid a frustrating surprise.
It’s also worth knowing that federal reporting requirements generally apply to cash transactions of $10,000 or more, or patterns of smaller transactions that appear structured to avoid that threshold — a much higher bar than most everyday withdrawals. If a smaller transaction is being questioned closely, it’s fair to ask a manager directly what specific bank policy, rather than personal curiosity, is prompting the question.
If a specific interaction feels like it crossed a line, most banks have a formal customer feedback or complaint process, and consistent patterns of complaints about a specific branch or policy are generally what actually prompts a bank to revisit how staff are trained to handle these conversations.
You can watch the full video and follow @debteach20 on Instagram for more.
Leave a Reply