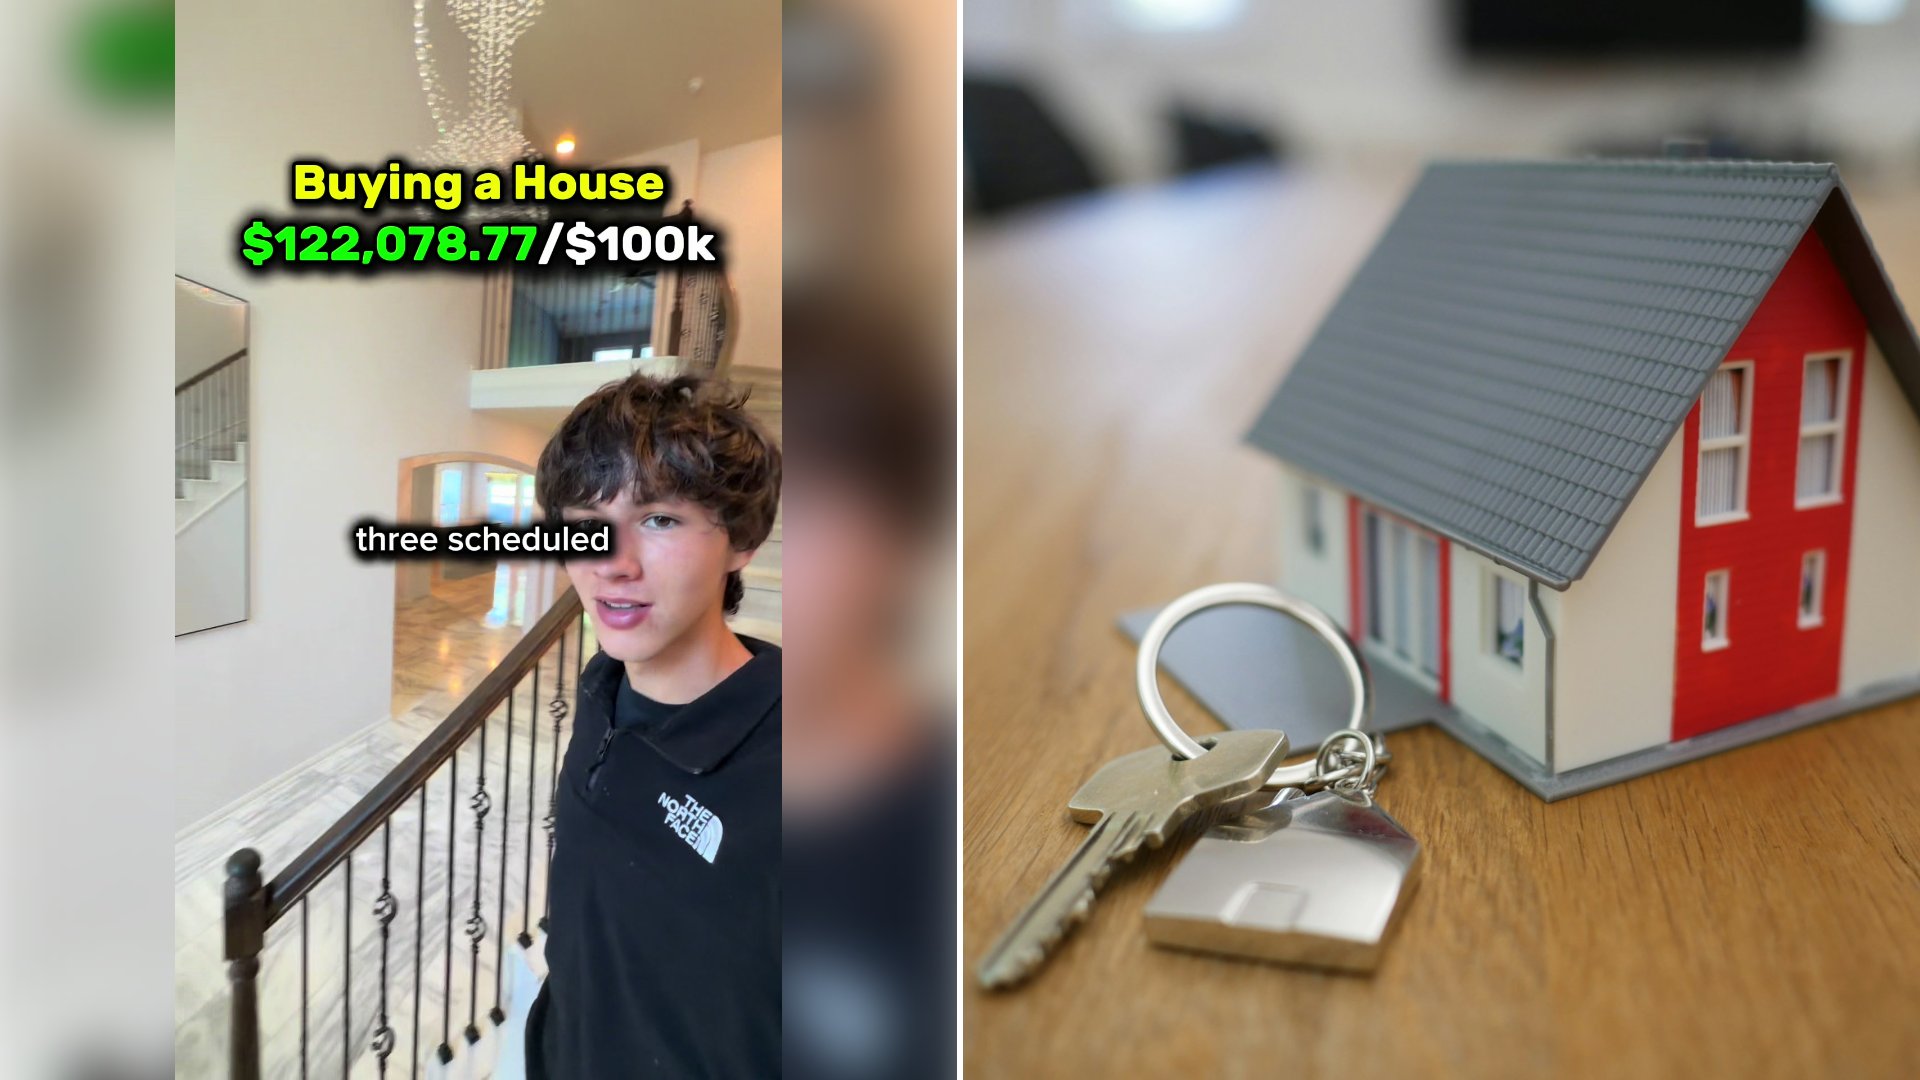
House hunting as a first-time buyer is stressful enough in private. Creator @landenlevine1 is doing it entirely in public, posting a running series that follows every house tour, every setback, and every bit of progress toward the budget he’s trying to hit before he can actually make an offer.
@landenlevine1
The series follows a format that’s become increasingly popular among young buyers on social media: documenting the full emotional and financial arc of house hunting rather than just posting a celebratory “we got the keys” video at the end. Viewers see the walkthroughs, the reactions to homes that don’t work out, and the honest accounting of how far he still has to go before hitting his target number. It’s a format that resonates because so much of the actual home buying process, the budgeting, the waiting, the repeated disappointments, normally happens entirely out of public view.
For young, first-time buyers navigating this process for real, the financial side of the equation has shifted noticeably in recent years. Saving toward a down payment and closing costs while also managing rent, student debt, and rising everyday costs has pushed many buyers toward specific assistance programs designed to narrow that gap, rather than relying purely on personal savings.
First Time Buyer Assistance Options Worth Knowing About
Most states run their own first-time homebuyer assistance programs, typically administered through a state housing finance agency, and they generally fall into a few common categories:
- Down payment assistance grants or forgivable loans. Many state programs offer a set amount or percentage toward a down payment, often forgiven entirely if the buyer stays in the home for a minimum number of years.
- Below-market interest rate mortgages. State housing finance agencies frequently partner with approved lenders to offer first-time buyers a lower rate than the general market, sometimes combined with reduced mortgage insurance requirements.
- Income-qualified eligibility tiers. Most of these programs cap eligibility based on household income relative to the area’s median, meaning a buyer’s eligibility can vary significantly depending on which county or metro area they’re buying in.
- Mortgage Credit Certificates. Offered in many states, these let qualifying buyers claim a portion of their annual mortgage interest as a direct federal tax credit rather than just a deduction, which can meaningfully reduce the real cost of homeownership in the early years.
- FHA-backed loans with lower down payment minimums. While not state-specific, FHA loans remain one of the most commonly used tools for first-time buyers precisely because they allow a significantly lower down payment than many conventional loan products require.
Eligibility and benefits vary considerably by state and sometimes by county, so the practical first step for any buyer in this position is checking directly with their state’s housing finance agency website to see which programs apply to their specific income bracket and target purchase price. Many of these programs also have a limited pool of annual funding, meaning timing can matter as much as qualifying in the first place.
Whatever the exact details of this particular buyer’s budget and timeline end up being, the series has clearly tapped into something a lot of young buyers relate to: house hunting rarely moves in a straight line, and documenting the real version, tours that don’t pan out included, tends to land better with an audience than a highlight reel ever could. Viewers will likely keep watching to see how much closer the next update brings him to his goal.
More from Willow and Hearth
- National Association of Realtors Says the Typical First Time Buyer Is Now 40 Years Old and Puts Down 10 Percent, According to Its 2025 Profile of Home Buyers and Sellers
- Federal Housing Finance Agency Raises the 2026 Baseline Conforming Loan Limit to $832,750 and Caps High Cost Areas at $1,249,125, Which Leaves Some Buyers Still Borrowing Jumbo
- Freddie Mac Survey Puts the Average 30 Year Fixed Mortgage Rate at 7.40 Percent for October 8, Adding About $24.50 a Month to a $300,000 Loan Compared With the Week Before
Leave a Reply